For many Nigerians, the exhortation that the country must move “from consumption to production” sounds like a message meant for government officials, industrialists and wealthy people who have access to land, capital, technology and other factors of production.
That perception misses an important point.
While the size of our resources may differ enormously, virtually everyone possesses some form of economic resource. The critical difference is often not simply what we have, but what we do with what we have.
And that brings us to mindset.
The current Initial Public Offering (IPO) of Dangote Petroleum Refinery and Petrochemicals offers an interesting case study in how an ordinary Nigerian can begin to think differently about money—not merely as something to spend, but also as something that can acquire ownership and potentially create future wealth.
The offer, which opened on September 14, 2026, comprises 4.1 billion ordinary shares at ₦525 per share, with a minimum subscription of 10 shares, or ₦5,250. The offer is scheduled to close on October 13, 2026. The proceeds are intended to support the refinery’s expansion programme.
Aliko Dangote has described the IPO in terms of broadening participation in wealth creation. The idea is striking: the refinery, one of Africa’s largest industrial projects, is being opened to eligible investors who can participate with a relatively small amount of money.
That is why the IPO has generated so much excitement beyond the traditional investment community. Reuters reported a wave of social-media jokes and memes about ordinary Nigerians suddenly becoming refinery “co-owners”, board members and partners.
And who can blame them?
Imagine a driver, artisan, domestic worker, trader or young professional being able to say, quite legitimately, “I own shares in the Dangote refinery.”
The psychological significance of that statement may be greater than the immediate monetary value of the shares.
The democratisation of ownership
There is a difference between political democracy and financial-market participation.
Political democracy gives citizens a vote. The capital market gives investors an opportunity to own a stake in businesses.
One is about political representation; the other is about economic co-ownership.
The Dangote offer is particularly interesting because of its relatively low entry point. At ₦525 per share and a minimum subscription of 10 shares, someone who can legitimately spare ₦5,250 can participate, subject to the eligibility and allotment terms of the offer.
There is no ethnic, religious or geographical allocation formula in the ordinary sense of Nigeria’s political arrangements. What matters is whether an applicant meets the conditions of the offer and what the eventual allotment is.
But we should be careful about turning this into a fairy tale.
An IPO is not a guaranteed route to wealth. Shares can rise, fall or remain stagnant. The Dangote IPO itself carries investment risks, and the company’s official IPO materials explicitly warn prospective investors that they may lose part or all of their investment.
That warning is important.
The point of this article, therefore, is not to tell anybody to buy Dangote shares. It is to ask a more fundamental question:
What could happen if Nigerians began to see even small amounts of disposable money as potential capital rather than automatic consumption?
The N5,250 question
This is where the conversation becomes particularly interesting.
There are Nigerians for whom ₦5,250 is not spare money at all.
For some households, it may represent food. For others, transport. For someone living from one day’s earnings to the next, losing a day’s income because of illness, rain or lack of customers can create a serious problem.
So let us establish something clearly:
Basic needs are not consumption that should be postponed in favour of investment.
Food, essential medication, shelter and other necessities must come first.
But there is another category of expenditure: wants.
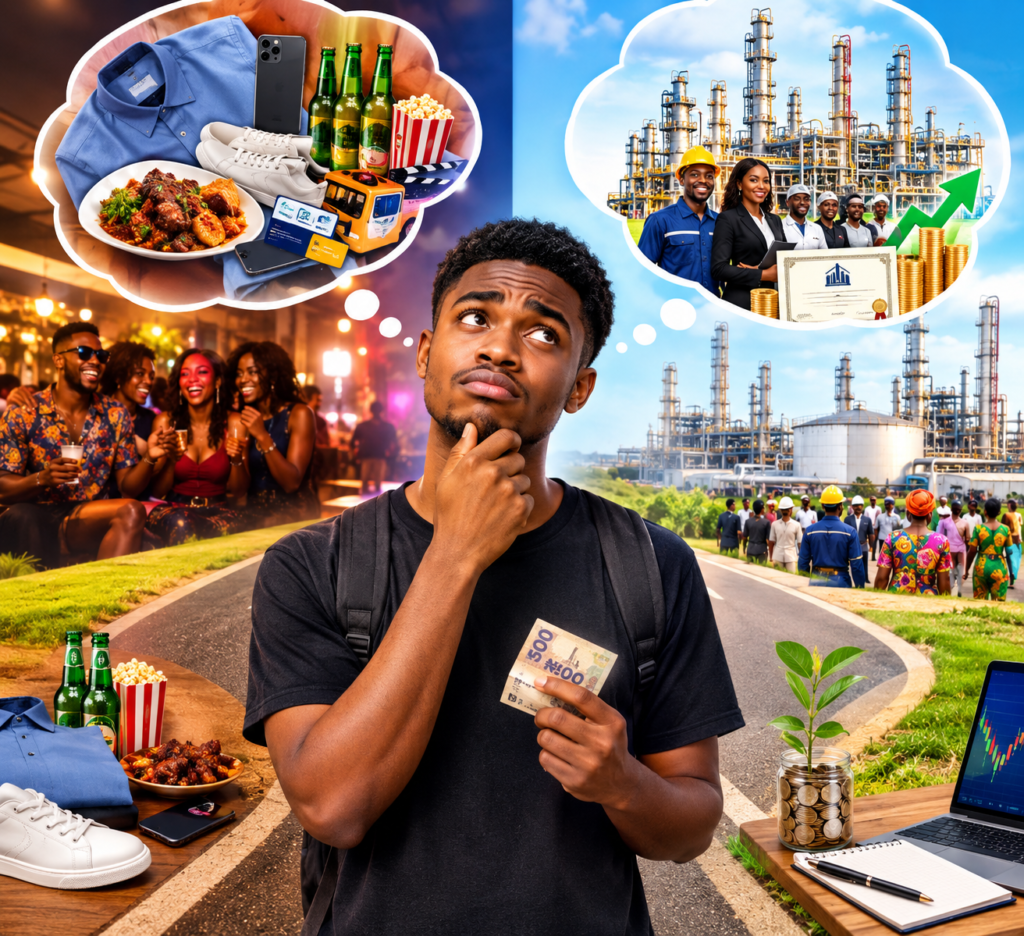
For a young Nigerian who genuinely has ₦5,250 available after meeting essential obligations, what could that money buy?
A shirt.
Transport for a day or two.
Data.
A haircut.
Suya, pizza or shawarma.
A few bottles of beer and pepper soup.
A cinema outing.
A television subscription.
Or any of the countless small pleasures through which we make life more enjoyable.
There is nothing inherently wrong with any of these things.
The question is simply:
Which of them can I postpone today in exchange for a possibility of greater financial benefit tomorrow?
That is the real meaning of the consumption-versus-investment debate.
Consumption today or ownership tomorrow?
A rational financial decision is not necessarily about denying yourself every pleasure.
It is about distinguishing between needs, wants and investments.
Needs have to be met.
Wants can sometimes be postponed.
Investments are sacrifices made with the expectation—never the guarantee—of future returns.
That distinction is particularly important for young people because they have something older people have less of: time.
Time allows relatively small amounts of money to compound.
A person who develops the habit of saving and investing early may have decades for those investments to grow. A person who postpones the habit until middle age or retirement has less time for compounding to work.
This is why financial literacy matters.
The challenge is not simply to tell young Nigerians, “Stop consuming.”
That would be unrealistic.
The more useful message is:
Learn to consume consciously, save deliberately and invest intelligently.
What does ₦5,250 really mean?
The history of the Nigerian capital market offers some fascinating illustrations.
Consider some well-known companies that entered the market years ago. An investment made at their original offer or introduction prices would have produced dramatically different outcomes depending on the company, subsequent corporate actions, dividends, market conditions and the timing of entry and exit.
For example, Zenith Bank’s share price was ₦10.90 at its 2004 introduction, while its market price was ₦128 on September 21, 2026. Similarly, GTCO, which has undergone corporate restructuring since its original Guaranty Trust Bank listing of 2004 at N10.60, closed at ₦133.90 on the same day, September 21, 2026. That is capital appreciation.
Dangote Cement, introduced on the Nigerian market in 2010, provides another illustration. Its shares traded at ₦135 on introduction 16 years ago, and ₦1,066.70 on September 23, 2026.
The Nigerian Exchange Group (NGX) itself was listed at N17.17 in 2021 and ₦185 on September 23, 2026.
These figures make an important point—but not necessarily the one sometimes drawn from them.
The stock market can create substantial wealth, but not every stock does so, and past performance does not guarantee future performance.
African Insurance is an example of an investment that has performed poorly in recent years. That is an equally important part of the story.
The market has winners and losers.
The lesson, therefore, is not “put your money in shares and you will become rich.”
The lesson is:
Understand what you are buying. Understand the risk. Diversify where appropriate. Think long term. And do not confuse investing with gambling.
A note about the numbers
It is tempting to take ₦5,250 invested in a company years ago, convert the money into dollars at the exchange rate of the time, convert that dollar value back into today’s naira and then compare the result with today’s share price.
That can be useful as an illustration of the effect of currency depreciation.
But it is not the same thing as calculating the actual investment return.
An actual historical investment calculation must account for the number of shares originally purchased, subsequent share splits or consolidations, bonus issues, rights issues, mergers or restructurings, dividends received and reinvested, transaction costs and other corporate actions.
That is why apparently spectacular historical figures should be treated carefully.
For instance, saying that ₦5,250 invested in Zenith Bank in 2004 would be worth hundreds of thousands of naira today may be a useful illustration under a particular exchange-rate methodology, but it should not be presented as the actual value of the original shareholding without reconstructing all the intervening corporate actions.
This distinction matters because financial education should not become financial mythology.
The real investment is the mindset
Perhaps the most important thing about the Dangote IPO is not the ₦5,250.
It is the habit it could encourage.
Imagine a young Nigerian who has never owned a share before.
He or she learns what an IPO is.
Learns how the stock market works.
Reads a prospectus.
Understands dividends and capital gains.
Learns that share prices can fall as well as rise.
Begins following company results.
Learns about risk and diversification.
Then perhaps invests another ₦5,000, ₦10,000 or ₦20,000 in another company after doing proper research.
The person has crossed an important psychological boundary.
He is no longer merely a consumer.
He has become a participant in the economy.
That is the bigger idea behind moving from consumption to production.
Strictly speaking, buying shares does not make the investor a producer. The company produces the goods and services.
But investment makes the shareholder a capital provider and co-owner of productive enterprise.
And that distinction is important.
Instead of only buying what businesses produce, you can, where your circumstances permit, also own a tiny part of the businesses producing them.
The parable of the talents
There is an old biblical parable about talents.
Its economic lesson is remarkably contemporary: resources can be preserved, deployed or multiplied, and the decision about what to do with what one has carries consequences.
But there is another lesson we should not miss.
Not everybody has the same starting point.
One person may have ₦5,250.
Another may have ₦5 million.
Another may have nothing left after buying food.
Financial wisdom therefore cannot mean telling everyone to make the same investment decision.
It means understanding one’s circumstances and making informed choices.
For the person who cannot afford ₦5,250, there is no shame in not investing.
For the person who has ₦5,250 but has urgent competing needs, those needs should be considered first.
For the person who has met essential obligations, has an emergency cushion and is considering what to do with surplus money, the question becomes different.
Can I sacrifice one small consumption today to acquire a potential financial asset for tomorrow?
That is a question worth asking.
The bigger Dangote lesson
Nigeria has spent decades exporting crude oil and importing refined petroleum products. The Dangote refinery represents an attempt to move more value addition into the domestic economy. The refinery is currently operating at large scale, and the IPO is intended to raise ₦2.15 trillion to support further expansion.
That makes the IPO more than another stock-market transaction.
It is also a conversation about ownership.
Who owns productive assets?
Who supplies capital?
Who receives dividends?
Who benefits when Nigerian businesses grow?
For too long, many Nigerians have approached wealth primarily from the consumption end of the economic chain. We earn money and spend it. We buy houses, cars, clothes, phones, food and entertainment.
All of that is necessary.
But a society that wants broad-based prosperity must also develop a culture in which ordinary citizens own productive assets.
That is where the real significance of the Dangote IPO may lie.
So, what will you do with your ₦5,250?
The question is not whether everyone should buy Dangote shares.
The question is whether every Nigerian who has some disposable income should begin asking a different question:
How much of my money should I consume today, how much should I save, and how much can I invest in something that may produce value tomorrow?
For one person, the answer may be Dangote Refinery.
For another, it may be a bank stock.
For another, a government security, mutual fund, small business, professional training or another productive asset.
And for someone struggling to meet basic needs, the answer may simply be: survive today first.
There is wisdom in all three positions.
But for those who can afford to take a measured investment risk, the ₦5,250 question is worth considering.
Would you rather spend the entire amount today on something you will barely remember next year?
Or could part of your disposable income be deployed into an asset whose future value you cannot know today—but whose potential you have taken the time to understand?
That is not a question about Dangote alone.
It is a question about how we think about money.
The journey from consumption to production does not necessarily begin in a government policy document or a billion-naira factory.
Sometimes, it begins with an ordinary person looking at ₦5,250 in his or her hand and asking:
“Must I spend all of this today?”
That question may be small.
The mindset behind it is not.
*Emeka Onyenacho is a retired commercial banker and financial-services expert based in Lagos.
